Australian Bitcoin Holders: Tax Mitigation Strategies Before the 2027 CGT Reform - Part 1
Cryptocurrency holders in Australia are bracing for a substantial capital gains tax increase taking effect in July 2027. Discover essential tactics to prepare for these regulatory changes and reduce your tax obligations.
When the Australian government announced the elimination of the 50% capital gains discount across all investment classes in their May budget announcement, cryptocurrency investors were caught off guard. This new framework essentially increases the taxable portion of any capital gain by double, with only a minimal adjustment for inflationary effects.
However, legitimate approaches exist to reduce your CGT liability — provided you begin planning immediately.
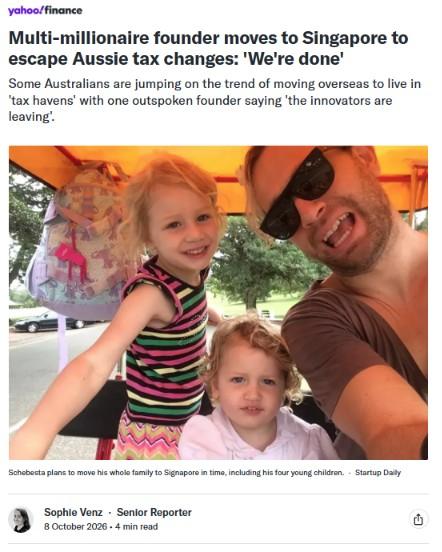
Certain Australian cryptocurrency investors are pursuing extreme options — such as Finder's founder and prominent crypto advocate Fred Schebesta, who has chosen to move to Singapore where capital gains tax stands at 0%, declaring the tax modifications were a "killer blow." Alternative, less extreme approaches to lowering CGT obligations exist, including establishing a self managed super fund (SMSF), creating a corporate entity to conduct crypto transactions at corporate tax rates, or simply maintaining optimism that opposition parties will overturn these modifications following the upcoming election.
What's changing with CGT on July 1, 2027?
Beginning in 1999, Australian asset holders have been required to pay tax on only fifty percent of their capital appreciation. Starting July 1, 2027 they'll be taxed at their complete marginal income tax rate — translating to 30% CGT when your combined income and gains fall between A$45,000 and $135,000, 37% on the segment between $135,000 and $190,000 and 47% for amounts exceeding that threshold. (All figures in this story are in Aussie dollars)
Making matters worse, individuals earning lower incomes who don't receive welfare benefits such as students and those in retirement will face a mandatory 30% CGT rate regardless of how minimal their gain might be.
The sole discount currently available takes into account how inflation impacts your initial cost basis. Therefore if you purchase a property for $1 million in 2027 and dispose of it for $1.5 million following a 10 year period, assuming inflation runs at 3%, you won't owe tax on roughly $344,000 that's attributed to inflationary increases.
"The challenge for cryptocurrency is that the CGT changes, indexation really helps slower growing assets not fast ones," explains Andrea Yuen, Swyftx CEO.
Therefore if you purchased Bitcoin at $10,000 and liquidate it a decade later at $100,000, the inflation adjustment amounts to only approximately $3,439. Under the previous framework you would face tax on $45,000 in gains. Under the revised framework you'll face tax on $86,561 in gains.
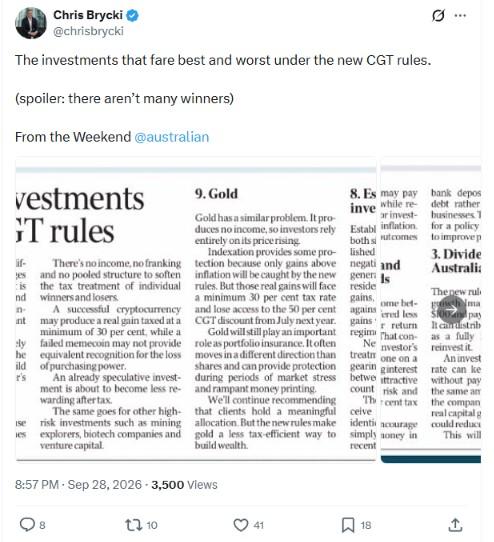
Stockspot analyst Chris Bryki compared how ten different asset classes would fare under the new rules. "Crypto sits at the bottom because almost its entire return comes from capital growth," he wrote in The Australian newspaper.
An already speculative investment is about to become less rewarding after tax.
Below are several different approaches to assist cryptocurrency holders in managing the modifications, spanning from minimal to no effort, through to completely restructuring your circumstances.
1. Hope for a massive bull run before July
Any appreciation you've accumulated prior to July 1 2027 will fall under the current 50% discount framework. Therefore your optimal scenario is hoping a powerful bull market drives your portfolio's value to the highest level achievable before that deadline. You must diligently document the worth of each crypto asset in your possession on that date, since any appreciation from that baseline will be subject to taxation at the increased rate.
Ben Simpson, founder of crypto advisory service Collective Shift, says Bitcoin's performance since mid-year in a challenging macro environment bodes well for further gains before July.
However Simpson (who points out he's not a financial advisor) adds, "I probably wouldn't be betting the farm on the fact that we're gonna have a huge bull run"
I think the halving in May 2028 is where we'll see most of the returns. So I don't think it's going to work in investors' favor.
Yuen notes that prices aren't within your control. "A strategy isn't a strategy if you're just sort of hoping," she says.
2. Vote for a party that will reverse the CGT changes
Both the official opposition The Coalition, and the insurgent opposition One Nation, have promised to reverse the changes. Crypto voters who feel strongly enough about this single issue, could vote for a change in government. However, the ruling ALP holds 94 out of 150 seats in the House of Representatives and will be difficult to dislodge from office. If the government does change — and the legislation can pass the Senate in time — it's technically possible the changes could be reversed before anyone has to file taxes from July 1 2028.
Yet there's likely a greater probability that any modifications to the framework would materialize following that deadline. Adrian Forza, director of Crypto Tax Australia, says this would make calculating gains very difficult.
It would be a nightmare to do three calculations, but longer term, it'll be better for the public.
3. Shift your crypto into a self-managed superannuation fund
Retirement accounts in Australia are known as superannuation funds, and upon reaching age 60 you gain access to your investments without tax obligations — even while they continue appreciating. Regrettably none of the retail super funds permit customers to invest in crypto, therefore if you wish to shield your crypto appreciation using this approach, you'd need to establish an SMSF. Approximately one-third of Simpson's high net worth clients invest in crypto via SMSFs. "Buying Bitcoin and accumulating it there is a super solid idea," he says, although he cautions against adding many altcoins. "You're risking your retirement, which is an ultra long-term hold, on short-term altcoins," he says.
The significant disadvantage with SMSFs — the 27-year-old founder clarifies — is that younger cryptocurrency investors face decades before accessing the funds.
You can't touch it until you're in retirement, right? So you can't really utilize any of those gains until later in life.
In practical terms then, this approach proves more appropriate for wealthier investors beyond age 50, who face a shorter waiting period.
The government has also transformed managing an SMSF into a bureaucratic burden, requiring extensive compliance documentation and audits, plus a collection of mandatory fees that render it impractical for smaller account balances. Yearly expenses typically fall between $2,000 and $4,000, though digital platforms like Stake can decrease total annual expenses to approximately $1,330, provided you exclusively purchase Bitcoin or Ether ETFs.
You're also required to liquidate any cryptocurrency and settle taxes on it prior to repurchasing it through your SMSF, and annual contribution caps must be considered, though Forza says you should be able to get almost $400,000 in there with a bit of creativity.
Keep an eye out in December for a detailed report on how to set up a crypto SMSF.
4. Borrow against your Bitcoin to avoid a CGT event
One tactic certain billionaires use to sidestep tax obligations involves borrowing against their holdings, since loan repayment frequently proves less expensive than paying tax following a sale.
Bitcoin holders can now utilize various lending platforms, such as BlockEarner, Veild and Swyftx, enabling you to implement a comparable approach by obtaining loans with your BTC serving as collateral.
"We like to bring that strategy to the masses, not just to billionaires," laughs Yuen.
Yet this approach carries risk without a billionaire's substantial financial reserves. Borrowers encounter elevated interest charges, relatively brief loan terms (usually 12 months), and face the possibility of forfeiting their Bitcoin should market conditions turn unfavorable. You cannot borrow against the complete value either — Swyftx maintains a loan-to-value ratio around 40%. "If your collateral drops below a certain amount, there will be a margin call," she says. "I would say it's a bet on a price going up. I think you have to have a view that crypto will go up — or at least not go down so that you get margin-called... Otherwise, a crypto-backed loan wouldn't make sense for you."
Simpson doesn't recommend this strategy due to the risks, but says it can pay off for some people. For example if you borrow at 10% interest, and Bitcoin compounds by 33% a year (as it has done in the past) you'd end up much better off than paying CGT.
However he cautions it represents a leveraged wager that suits sophisticated investors best.
I wouldn't recommend it for someone that's highly exposed to crypto and doesn't have the capital behind them because it's a risky thing if you don't know what you're doing.
Bitcoin is down 28% over the past year, so anyone borrowing a year ago would have faced margin calls and possible liquidation as well as interest costs.
Forza warns that cryptocurrency borrowing can also trigger a CGT event under certain conditions, including borrowing within DeFi. When you deposit ETH to Aave, it undergoes automatic conversion to WETH which constitutes a taxable event, and upon withdrawing the ETH it triggers another taxable event.
Obtaining loans from centralized lending services like BlockEarner or Swyftx remains currently uncertain territory, and the ATO has not provided clarification regarding whether it constitutes a taxable event. "If you're talking about [borrowing] ten grand fine. But if you've got three to five Bitcoin, I wouldn't risk it because if it goes against you then you're going to be paying tax." "Vield is the only one in Australia that's got a private ruling that says their product is not a taxable event. No one else has got one." Swftxy confirmed it has not got a private ruling and said clients should seek tax advice, while BlockEarner did not respond to a request for comment.
In part two of our Aussie CGT special, coming later this week, we'll bring you the final four strategies to minimize your crypto tax bills, including setting up a company or leaving the country entirely.