Is relocating from Australia worth it to escape the 47% cryptocurrency tax?
A growing number of Australian cryptocurrency holders are relocating internationally to escape the substantial CGT rise scheduled for July 2027. However, alternative strategies exist that are considerably less extreme for reducing your tax burden.
The first installment of our comprehensive guide on navigating Australia's significant capital gains tax increase for cryptocurrency assets starting next July examined strategies including leveraging your Bitcoin holdings as collateral and establishing a self-managed super fund (SMSF), representing four different approaches to lessening the tax burden.
An SMSF provides Australian investors with the most substantial tax benefits available, though it's primarily appropriate for those approaching retirement age, or individuals prepared to keep their cryptocurrency assets locked away for multiple decades until reaching retirement. Younger cryptocurrency holders might find that relocating internationally could eliminate their future crypto taxation entirely to 0% — though there exist alternative approaches that are considerably less extreme for achieving tax savings.
5. Leave Australia and move to country with 0% CGT
The looming tax policy modifications in Australia have already motivated cryptocurrency entrepreneur Fred Schebesta, who established Finder.com, to relocate as a tax expatriate to Singapore.
Starting in July, the maximum rate applied to genuine, long-term cryptocurrency profits will climb to 47%, with adjustments made for the inflation impact on the original cost basis.
For ambitious, unattached cryptocurrency holders, the extreme measure of departing the nation to prevent surrendering nearly half of their investment returns to the tax authorities appears progressively more appealing. Numerous leading global cryptocurrency centers — Singapore, Portugal, Malta, UAE and Hong Kong — provide 0% capital gains taxation on long-term cryptocurrency profits as part of their strategy to draw affluent investors.
Ben Simpson, who established the cryptocurrency consulting firm Collective Shift, indicates that several of his community members have already made this decision.
"Yeah, we've had a number of people that have sort of packed up and gone basically, 'f—- this. I'm off to the Bahamas or whatnot,'" he says.
Andrea Yuen, CEO of Sywftx, acknowledges she fully understands the taxation benefits associated with residing beyond Australia's borders.
"I lived in Singapore for 30 years. I do miss my no capital gains tax," she says. However, she clarifies that tax considerations weren't her motivation for relocating there, and warns that completely uprooting one's existence to dodge some taxation represents a fairly extreme measure.
"I would never say that we should structure our lives only to think about tax outcomes," she says. "There are many other wonderful reasons why I've come back to Australia and continued to live in Australia."
"I think if you're moving countries solely based on a decision about whether you know your crypto is going to get taxed, then you probably need to think a little bit harder."
Simpson has contemplated this possibility himself, considering he already dedicates six months annually in America managing Collective Shift US, though researching the regulations discouraged him.
"You really have to cut pretty much all ties to Australia. So if you are genuinely happy to leave and don't want to come back for the majority of the year, and cut your healthcare and cut all your ties back to Australia, then that is a strategy."
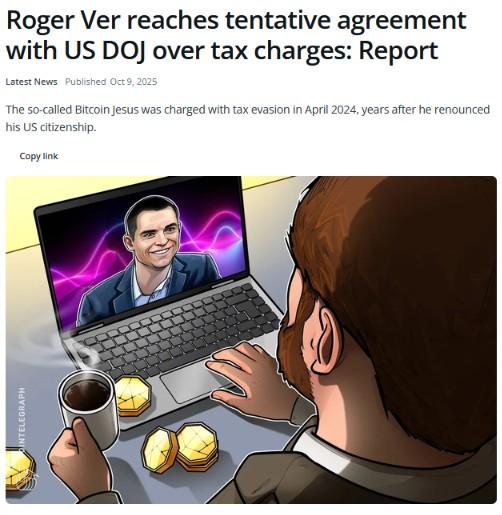
Roger Ver, known as "Bitcoin Jesus," renounced his US residency in 2014, and a decade later found himself arrested and charged with improperly reporting his cryptocurrency holdings' value and failing to pay exit taxes. He ultimately paid almost $50 million to resolve the legal proceedings. In a similar fashion, Australians departing the country encounter a substantial exit tax upon leaving, potentially necessitating the liquidation of a considerable portion of your cryptocurrency holdings.
"They tax you on the way out. If you've got a lot of gains or profits you're sitting on, they'll catch you when you leave," says Adrian Forza, director of Crypto Tax Australia. "Arguably it'd be bigger in the future, but it's still difficult to stomach selling off everything to leave."
Forza clarifies you alternatively have the choice of settling the Australian taxes at a future date, though calculated on the complete value of the profit after you liquidate the asset. Therefore if you anticipate Bitcoin's value rising, settling the exit tax immediately would be your optimal choice.
6. Set up a company to benefit from the company tax rate
Simpson is only 27 and finds the idea of securing his crypto portfolio away for four decades quite unappealing. As an alternative, he conducts trades and maintains crypto through a company structure to take advantage of the 25% company tax rate.
Operating a single-person company structure is more straightforward than one might imagine, though not worthwhile unless you possess substantial capital and plan to execute numerous trades. It necessitates registering the company with ASIC and covering an annual fee, compensating an accountant to generate financial statements and/or an annual company tax return and dealing with payroll software and payday superannuation contributions should you choose to draw an income. You have the flexibility to distribute a dividend whenever you require funds.
"The company structure is good if you're wanting to cap the capital gains tax at the company tax rate," he says, though points out there's a significant drawback: when you extract funds from the company, you must pay the difference between the 25% company tax rate and your personal tax rate.
"You still need to pay your marginal income tax rates. If you're on the top tax rate, like 47%," he says.
You might be questioning: if you must ultimately pay your income tax rate regardless, which will match the CGT rate starting July, what benefit exists in spending several thousand dollars and completing extensive paperwork to operate a company?
Simpson clarifies that the primary benefit is that during the period you're expanding your crypto portfolio through trading different coins, you only remit the 25% company rate for every sale. This translates to paying as much as 22% less than CGT whenever you close a position, which compounds into an even more substantial saving across time.
"Instead of paying 47% because you've just taken the profits… then the CGT amount is only 25% — the company tax rate. So when you put that money back in, you've got more capital to play with."
Nevertheless, if your trading volume is insufficient, it might face taxation at 30%.
Forza indicates the benefits are more pronounced for individuals with higher incomes.
"If you're a single person, then you've got a company, and you're earning, you know, 150 grand a year, um, or over 200, then yeah, definitely a company would be the way to go, especially now that the CGT discount has gone out the window."
It's not an especially beneficial structure if your intention is simply to hold your Bitcoin, though. Some potential benefits exist but arguably insufficient to justify the complications.
7. Just get out of crypto entirely to avoid high CGT rates
The 50% CGT discount has been substituted with an indexation discount, which accounts for the extent inflation impacts your original purchase price for an asset.
This signifies that investors who purchase and retain dividend stocks or index funds across an extended period will obtain a larger CGT discount. So does this mean you should abandon crypto and acquire a collection of ETFs to reduce your tax liability?
The straightforward response is no: the revised CGT 'discount' is predominantly an illusion, as it merely calculates your actual gain after accounting for inflation.
Simpson acknowledges crypto has suffered significantly from the CGT modifications, though it continues to provide the superior risk-reward proposition.
"For us in Bitcoin, the growth ... heavily outweighs the tax considerations. In my point of view. If you've got the right portfolio, that can give you the right upside."
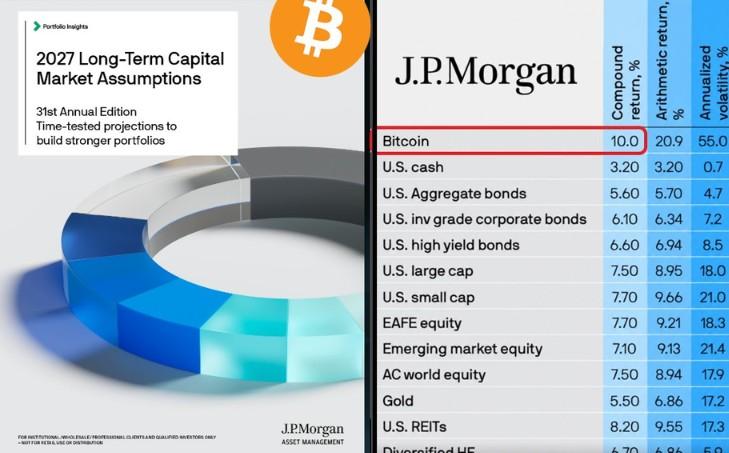
Historical data indicates that notwithstanding volatility and multi-year bear markets, the returns from Bitcoin investment over extended periods would continue to position investors advantageously compared to ETF investors even following higher tax payments. Investing further along the risk spectrum with altcoins however, can either yield impressive returns or result in complete catastrophe.
Simpson shares that he persuaded his younger sister, who plays basketball professionally on a modest income, to invest in Bitcoin two years ago instead of depositing money into a savings account.
"She's up like 40% or 50% in her portfolio and she's like, 'wow, this is going to get me so much further towards buying a house one day than sitting in cash and losing 10% [to inflation over time]," he says.
"That's why I think Bitcoin makes so much sense to accumulate. And the tax considerations are not really there for most people I think."
Yuen emphasizes crypto represents one of the limited asset classes offering investors the opportunity to generate double-digit returns within just a few months, or to potentially double their investment. Even following payment of the new taxes, crypto investors achieving those kinds of returns will remain financially ahead.
"My dad always said to me, it's a good thing, if you've made profits, you should be happy to pay some tax on it."
Perhaps not thrilled about it, but you'll continue earning profits nonetheless.