Crypto tax reform bill wins decisive 38–5 approval in House committee
A comprehensive cryptocurrency taxation bill moved forward through the House Ways and Means Committee, featuring rules for network fees, wash trading, and income from mining and staking operations.
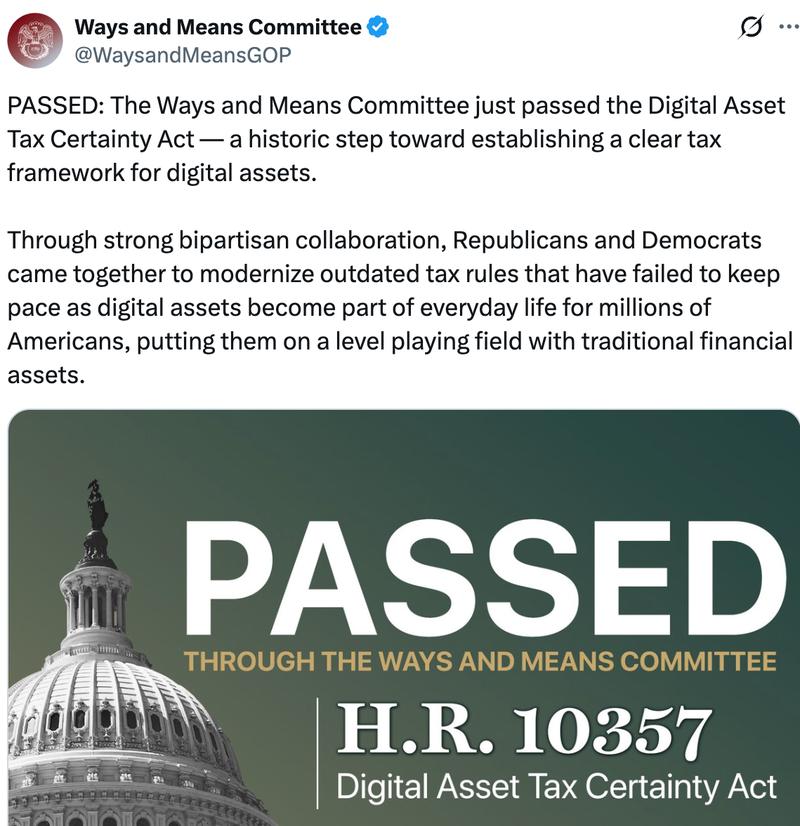
On Wednesday, the Digital Asset Tax Certainty Act received bipartisan backing from the US House Ways and Means Committee, marking a significant step forward for legislation designed to transform how federal tax law applies to digital assets.
The legislation moved forward with a 38-5 vote and addresses stablecoins, mining and staking operations, digital asset lending arrangements, transaction fees and additional cryptocurrency-related activities.
Key provisions within the bill include establishing specialized tax treatment for dollar-pegged stablecoins that meet qualifying criteria and certain lending agreements involving cryptocurrencies, applying wash-sale rules to digital assets that are widely traded, and creating new regulations governing income derived from mining and staking activities.
Additionally, the legislation would introduce a de minimis exemption applicable to certain cryptocurrency transaction fees, enabling taxpayers to forgo recognizing gains or losses in situations where digital assets are utilized to pay qualifying network or transaction fees totaling $10 or less.
Following the committee's approval, the bill now advances to the full House of Representatives where it will be taken up for consideration.
CLARITY Act failure shifts focus to regulators
The committee's vote occurred just one day following the Senate's inability to move forward with the CLARITY Act, a more comprehensive market structure bill designed to create a federal regulatory framework governing digital assets and delineate the distinct responsibilities of the Securities and Exchange Commission and Commodity Futures Trading Commission.
On Tuesday, the cloture motion was unsuccessful with a 49–50 vote, unable to reach the 60 votes required to move the legislation forward to debate on the Senate floor.
Following the vote, Senator Cynthia Lummis, who chairs the Senate Banking Subcommittee on Digital Assets and serves as a lead sponsor of the legislation, placed blame on Democrats for the bill's unsuccessful advancement.
For over a year, they presented demands and the second we met them, they made new demands and moved the goal posts.
Lummis stated in a post on X, further noting that Democrats had cast votes against proposed consumer protections and restrictions on politicians' personal crypto investments.
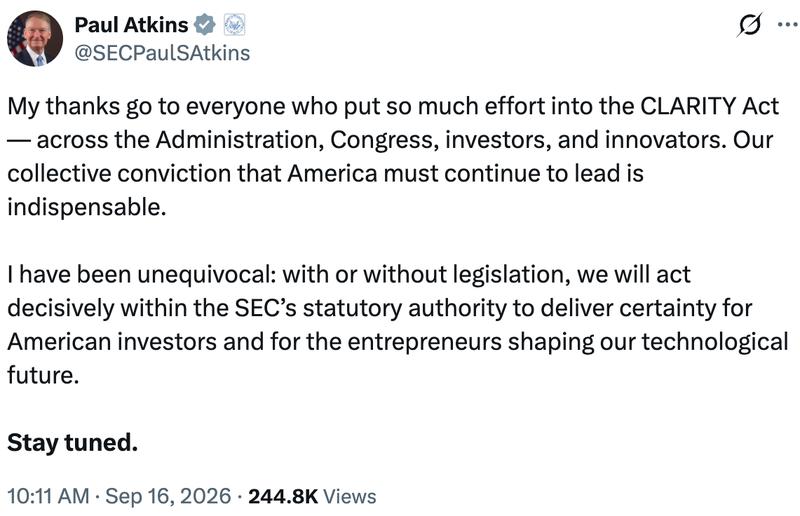
Following the bill's failure to move forward in the Senate, SEC Chair Paul Atkins indicated on Wednesday that the agency would proceed with cryptocurrency regulation utilizing its existing authority.
With or without legislation, we will act decisively within the SEC's statutory authority to deliver certainty for American investors and for the entrepreneurs shaping our technological future. Stay tuned.
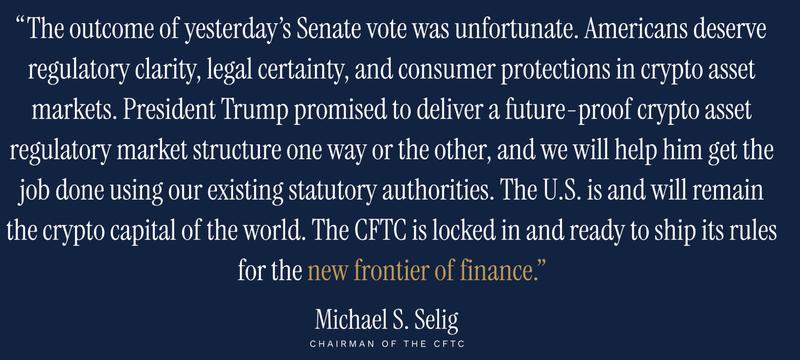
CFTC Chair Michael Selig mirrored Atkins' position, stating the agency would proceed forward utilizing its existing statutory authority notwithstanding the Senate vote.
The CFTC is locked in and ready to ship its rules for the new frontier of finance.
Selig stated in a Wednesday post on X, further adding that Americans "deserve regulatory clarity, legal certainty, and consumer protections in crypto asset markets."